The Term Spread As Recession Predictor, Post-2024
Source ↗
👁 0
💬 0
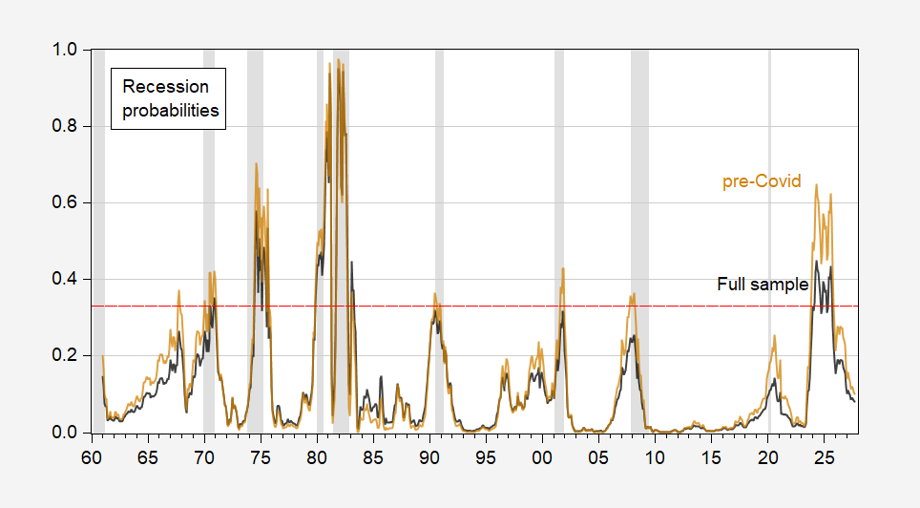
Using a plain vanilla term spread model (spread, short rate), what remains? From notes for tomorrow’s lecture.
Figure 1: Estimated recession probabilities from probit on 10yr-3mo term spread, short rate over 1960-2018 (brown), over full sample (black). Red dashed line at 33%. NBER defined peak-to-trough recession dates shaded gray. Source: author’s calculations, NBER.
Using a 33% threshold and the pre-2018 sample, the term spread catches every post-1960 recession (taking the pandem
Comments (0)